That is €65.00 duty and €244.95 recoverable VAT when the goods are declared under CN 3926 90 97 (TARIC, checked October 31, 2026). Then add EORI, freight and delivery to the warehouse.
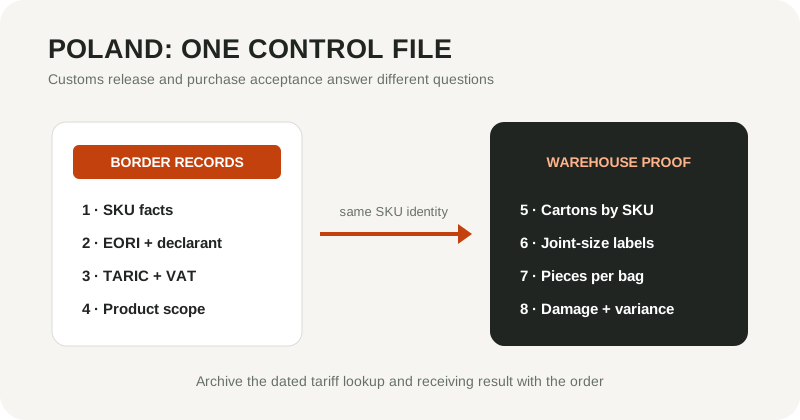
Bottom line: Customs release depends on a consistent product and declaration file. It does not prove that joint sizes, pack counts or labels match the purchase order.
5 checks to import tile leveling systems to Poland
- Confirm EORI and declarant.
- Use daily-updated TARIC.
- Confirm current Polish VAT treatment with the importer.
- Determine product-safety and CE scope.
- Quote the confirmed cargo and final warehouse.
Separate clips, pliers, kits and powered tools
Prepare a product sheet with composition, function, photos, manufacturing description and packaging. Save the classification rationale. Mixed kits and powered products should not borrow the result for a passive plastic component.
Add net weight, country of origin, unit count and the way the goods are presented at import. Give the same sheet to the broker and purchasing team, then archive the dated TARIC lookup with the order. Recheck the result after a material, motor, kit or packaging change.
Poland Import Cost per €1,000: 6.5% Duty + 23% VAT = €309.95
For tile leveling clips declared under CN 3926 90 97, Poland adds standard 23% import VAT to the EU duty. Worked per €1,000 of customs value:
| Line | Rate | Amount |
|---|---|---|
| Customs value (goods + freight and insurance to the EU border) | — | €1,000.00 |
| EU third-country duty | 6.5% | €65.00 |
| Poland import VAT on €1,065.00 | 23% | €244.95 |
| Border total | €309.95 |
Sources: European Commission TARIC, code 3926 90 97 90, third-country duty 6.50% for all origins including China, checked October 31, 2026; Your Europe VAT rate table (last checked by the Commission July 13, 2026), retrieved October 31, 2026. Customs value = goods plus freight and insurance to the EU border. The import VAT base also includes onward transport to the first destination in the member state, so the VAT line rises with those costs. Applies only when the declarant confirms CN 3926 90 97 for the exact SKU.
Of the €309.95, only the €65.00 duty is a final cost for a VAT-registered importer; the €244.95 VAT is normally recovered through the VAT return.
Model VAT and landed cost transparently
Separate goods value, origin handling, freight, insurance, customs value, duty, VAT, destination handling and inland delivery. Date every external input and show exclusions. Whether VAT is deductible depends on the importer and supporting records.
Use the importer of record and final warehouse as fixed assumptions. State the currency and exchange-rate date, then reconcile the customs entry to the invoice. This structure lets the buyer update one live input without silently carrying an old duty, tax or freight percentage into the next purchase.
Private-label controls
Freeze model, joint size, material, pieces per bag, Polish labeling where applicable, responsible-party information and carton marks. Review the legal role created by selling under the buyer's trademark before artwork approval.
Retain the approved artwork, photographed production sample and inspection result under the same model number. For a retail kit, verify both the individual components and the complete sale unit. Traceability should connect a complaint carton to the purchase order and production batch.
Route and receiving controls
Compare Gdańsk and alternatives using current total cost to the warehouse. On receipt, count cartons by SKU, inspect damage and verify joint-size labels and pack counts. Quarantine discrepancies before redistribution.
Require each route quote to state sailing, transshipment, free time, destination charges, customs support and inland delivery. Confirm final carton dimensions and gross weight after packaging approval. A port-to-port line is not comparable with a door quote unless exclusions are normalized.
Three purchase-order acceptance checks
Before balance payment or release, verify the approved material and break-off behavior, count pieces in a sampled bag, and match every model and joint-size label to the order. Record the sample size and result. These commercial checks answer a different question from customs clearance and should remain in the importer file.
Six records to retain
- SKU facts and sample
- EORI and declarant
- TARIC rationale
- Product-rule assessment
- Invoice, packing list and transport record
- Entry, tax and receiving reconciliation
Review our tile leveling clips, tile leveling wedges and tile leveling system wholesale supplier pages, then use the landed-cost method.
As the EU importer you are also the GPSR responsible person for China-made tools, and suction cups move to the Machinery Regulation on 20 January 2027; both are covered in GPSR for tile leveling tools.
Frequently asked questions
How much duty and VAT does Poland charge on plastic tile leveling clips?
If the declarant confirms CN 3926 90 97, the EU third-country duty is 6.5% and Poland adds 23% import VAT on customs value plus duty. Per €1,000 of customs value that is €65.00 duty plus €244.95 VAT, €309.95 at the border (TARIC and Your Europe, checked October 31, 2026).
What code applies to tile leveling systems in Poland?
If the declarant confirms CN 3926 90 97 (other articles of plastics) for plastic clips and wedges, the EU duty is 6.5% and Polish import VAT 23%: €65.00 + €244.95 = €309.95 per €1,000 of customs value (TARIC and Your Europe, checked October 31, 2026). Pliers, kits and powered tools need their own classification.
Does a Polish commercial importer need EORI?
Yes. An EORI number is mandatory for every economic operator making customs declarations in the EU; Polish businesses obtain it from the National Revenue Administration (KAS), and it is valid in all 27 member states.
Do tile leveling clips automatically require CE?
No. CE applies only to product groups covered by harmonised EU rules that mandate it. Other applicable product-safety and importer duties still require review.
Is Gdańsk always the best route?
No. Compare current sailing, destination charges, customs support and inland delivery. The final warehouse and cargo-ready date determine the useful route.